Insuring a Bull Terrier Against What It Actually Gets
Bringing a Bull Terrier into your life is an incredible joy, filled with laughter, boundless energy, and that signature goofy grin. But let's be realistic: owning one of these unique characters also means facing a specific set of health challenges that can quickly drain your bank account if you're not prepared. This guide is here to walk you through the often-confusing world of pet insurance, helping you understand how to best protect your Bull Terrier against the health issues that are, unfortunately, all too common for the breed.
The Unique Health Landscape of Bull Terriers
Bull Terriers, with their distinctive egg-shaped heads and mischievous personalities, are truly one of a kind. However, their genetics also predispose them to certain health conditions that future owners really need to be aware of. It's not about being alarmist, it's about being prepared and understanding what you might be up against, so you can make informed decisions about their care, and ultimately, your financial planning.
Kidney Concerns: Hereditary Nephritis and UPC Monitoring
One of the most devastating conditions for Bull Terriers is Hereditary Nephritis. This isn't just a simple kidney infection; it's a genetic disease that causes the kidneys to progressively fail, often taking dogs in their prime. It's heart-wrenching to witness, and the costs associated with diagnosis and management can be substantial. Owners often feel utterly blindsided, wishing they had known more or had better coverage.
The early detection of kidney issues often involves regular urine protein-to-creatinine (UPC) ratio monitoring. The Yearly Kidney Screen a Bull Terrier Needs for Life isn't just a suggestion; it's a critical part of proactive care. These tests, while not overly expensive individually, add up over a lifetime. If results indicate a problem, further diagnostics like ultrasounds and bloodwork become necessary, and that's when bills start to climb. Having insurance that recognizes the importance of these routine screenings, or at least covers the subsequent investigative work, can make a huge difference to your peace of mind and your wallet.
Imagine your vet calls and says your energetic three-year-old Bull Terrier, who seems perfectly fine, has a rising UPC ratio. This isn't a symptom you can see; it's picked up by routine testing. From there, you're looking at more frequent blood tests, perhaps a referral to an internal medicine specialist, and potentially starting your dog on medications or a special renal diet. Many Bull Terrier owners initially don't see the value in pet insurance until they are staring down a diagnosis like Hereditary Nephritis, at which point it's often too late to get coverage for that specific condition. Learning What a UPC Ratio Tells a Bull Terrier Owner can help you stay ahead of the game.
Heart Health: Mitral Valve Dysplasia and Aortic Stenosis
Another area where Bull Terriers need careful consideration is their heart. Conditions like Mitral Valve Dysplasia and Aortic Stenosis are unfortunately common. These are congenital heart defects, meaning they are present from birth, even if symptoms don't show up until later in life. A seemingly healthy Bull Terrier puppy can have a significant heart murmur that indicates a serious underlying issue.
Early screening for heart conditions is crucial. Vets will often listen for The Heart Murmur a Bull Terrier Puppy Should Be Checked For during initial exams. If a murmur is detected, an echocardiogram performed by a veterinary cardiologist is the next step to accurately diagnose the problem and assess its severity. These specialist consultations and diagnostic procedures are not cheap. For a condition that could require lifelong medication or even specialized surgery, pet insurance becomes a lifeline, ensuring you can afford the best possible care without having to choose between your dog's health and your savings.
Picture this: your happy, bouncy Bull Terrier puppy, full of beans, gets its first vet check. The vet hears a murmur. Suddenly, your excitement about your new family member is tinged with worry. You’re advised to see a cardiologist, and the cost of What a Bull Terrier's Echocardiogram Costs alone can be hundreds, if not thousands, of dollars. Then, if a condition like mitral valve dysplasia is confirmed, you're looking at ongoing cardiac monitoring, specialist visits, and potentially expensive daily medications for years. Without insurance, these costs can easily become overwhelming, forcing difficult decisions.
Skin Sensitivities and Allergies
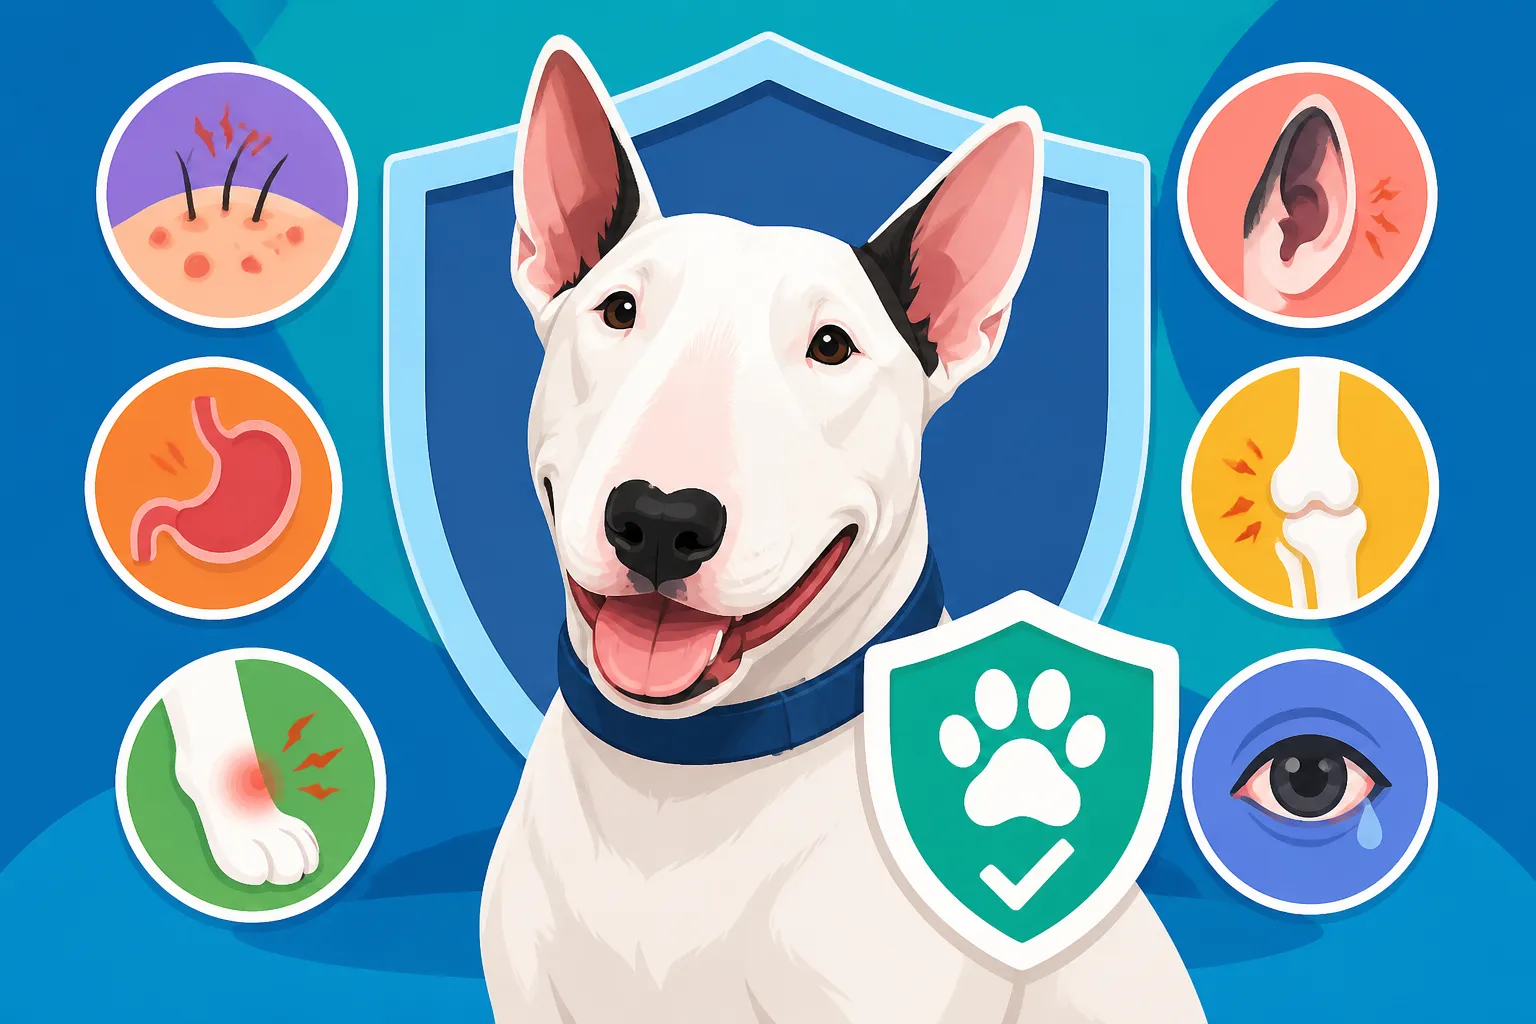
Bull Terriers, especially the whites, are often prone to a host of skin issues, making A Bull Terrier's Skin Is Its Weakest Point. From allergies that cause relentless itching and secondary infections to more specific conditions like zinc-responsive dermatosis, their sensitive skin requires diligent care and can lead to frequent vet visits. It's not just a cosmetic problem; chronic skin issues can severely impact a Bull Terrier's quality of life.
Managing skin conditions often involves a multi-pronged approach: special diets, medicated shampoos, allergy testing, antihistamines, steroids, or even newer, targeted medications. These treatments can be ongoing and costly. A Bull Terrier owner might find themselves rotating through different prescription foods, trying various supplements, and making frequent trips to the vet for injections or prescriptions.
For instance, your Bull Terrier might develop itchy paws and hot spots, leading to constant licking and chewing. A trip to the vet might suggest environmental allergies or food sensitivities. You embark on an elimination diet, which can be time-consuming and expensive, trying different limited-ingredient foods. Then comes allergy testing, followed by custom allergy shots or daily oral medication. These interventions are often lifelong commitments. Having insurance that covers diagnostics, prescriptions, and specialist dermatology visits can offer immense relief when dealing with these persistent, frustrating, and expensive skin problems.
Deciphering Pet Insurance: What's Covered and What Isn't?
Navigating the world of pet insurance can feel like trying to solve a puzzle with half the pieces missing. There are so many terms, different types of plans, and subtle clauses that can make all the difference when your Bull Terrier needs care. It's easy to get overwhelmed, but understanding the basics is crucial to choosing a policy that truly protects you.
Accident-Only vs. Accident & Illness Plans
When you're looking at pet insurance for your Bull Terrier, you'll generally encounter two main types of plans: accident-only and accident & illness. Accident-only plans are exactly what they sound like – they cover injuries from unforeseen events, such as a broken leg from jumping off the couch, swallowing a foreign object requiring surgery, or an emergency visit after a car accident. These plans are typically less expensive, but they offer very limited coverage, leaving you exposed to all those breed-specific health issues we just discussed.
Accident & illness plans, on the other hand, provide much broader coverage. They include everything an accident-only plan does, plus illnesses like cancer, diabetes, infections, and, critically for Bull Terriers, conditions like hereditary nephritis, heart disease, and skin allergies. While these plans come with a higher premium, they offer comprehensive protection against the vast majority of health problems your Bull Terrier is likely to face. For a breed with known genetic predispositions, an accident & illness plan is almost always the more sensible choice, even if it feels like a bigger upfront investment.
Imagine your Bull Terrier, in a moment of pure Bull Terrier exuberance, decides to chase a squirrel right off a small retaining wall and lands awkwardly, resulting in a fractured leg. An accident-only plan would likely cover the emergency vet visit, X-rays, and surgery to repair the fracture. However, if six months later your vet diagnoses your dog with a persistent ear infection due to allergies, an accident-only plan wouldn't touch those costs. An accident & illness plan would be there for both scenarios, offering a much wider safety net that accounts for the diverse health needs of your active, sometimes clumsy, and often allergy-prone Bull Terrier.
Understanding Deductibles, Reimbursement, and Annual Limits
These three terms are the bedrock of any pet insurance policy and understanding how they work together is key to predicting your out-of-pocket costs.
- Deductible: This is the amount you pay out of pocket before your insurance starts to reimburse you. It's usually an annual amount. Once you meet your deductible for the year, the insurance company will begin paying their portion of subsequent eligible vet bills. Some plans have per-condition deductibles, but annual deductibles are more common.
- Reimbursement Percentage: After your deductible is met, this is the percentage of the eligible vet bill that your insurance company will pay back to you. Common percentages range from 70% to 90%. If you have a 90% reimbursement rate, the insurance pays 90% and you pay the remaining 10%.
- Annual Limit: This is the maximum amount your insurance company will pay out in a policy year. Some plans offer unlimited annual coverage, which can be a huge benefit for chronic or catastrophic conditions. Other plans might have limits, for example, $5,000 or $10,000. Once you hit this limit, you are responsible for 100% of any further vet bills until the policy renews.
Let's put this into a real-world scenario. Your Bull Terrier is covered by a plan with a $250 annual deductible, 80% reimbursement, and a $10,000 annual limit. Early in the year, your dog has an acute gastrointestinal upset, costing $500 for diagnosis and treatment. You pay the full $500, which covers your $250 deductible, leaving $250 of that bill eligible for reimbursement. At 80%, you get $200 back. Later that year, your Bull Terrier needs surgery for a torn cruciate ligament, costing $3,000. Since your deductible is met, 80% of the full $3,000 ($2,400) is reimbursed, and you pay $600. So far, the insurance has paid out $2,600 towards your $10,000 annual limit, meaning you still have $7,400 in coverage remaining for any other unexpected health issues your Bull Terrier might encounter throughout the rest of the year. This helps you grasp What the First Year With a Bull Terrier Totals when unexpected health issues arise.
The Elephant in the Room: Pre-Existing Conditions
This is perhaps the most significant hurdle for many pet owners, especially those looking for insurance after their dog has already shown signs of illness. A pre-existing condition is generally defined as any illness or injury that your pet showed symptoms of, or was diagnosed with, before your insurance policy's effective date or during its waiting period. And here's the kicker: most pet insurance policies will not cover pre-existing conditions. This means if your Bull Terrier had skin allergies before you bought a policy, any future treatments for those allergies would be excluded.
The challenge for Bull Terrier owners is that some conditions, like Hereditary Nephritis or heart murmurs, can be present from birth but not manifest obvious symptoms until later. If a breeder hasn't conducted Which Health Tests a Bull Terrier Breeder Should Run and provided clear results, you might unknowingly acquire a puppy with a pre-existing condition. Some companies might distinguish between 'curable' and 'incurable' pre-existing conditions, potentially offering coverage for a curable one (like a single ear infection that resolves) if there have been no symptoms or treatment for a certain period. However, for chronic conditions, the exclusion is usually permanent. This makes the timing of when you get pet insurance absolutely critical for a Bull Terrier.
Consider a scenario where you've had your Bull Terrier for a couple of years, and he's suddenly developed a persistent cough. After vet visits and diagnostics, he's diagnosed with a heart condition. If you try to get pet insurance after this diagnosis, any treatment related to that heart condition will almost certainly be considered pre-existing and won't be covered. This highlights the vital importance of insuring your Bull Terrier as a young, healthy puppy, ideally before any murmurs are heard or UPC ratios start to rise, to ensure comprehensive coverage for potential future breed-specific issues.
Key Considerations for Insuring a Bull Terrier Puppy
Bringing home a Bull Terrier puppy is an exhilarating experience, filled with boundless energy, comical antics, and endless cuddles. It’s also the absolute best time to consider pet insurance, before any potential health issues have a chance to rear their heads. Being proactive here can literally save you thousands of dollars and countless heartaches down the line.
The Critical Window: Insuring Before Health Issues Emerge
For a Bull Terrier, the window of opportunity to get the most comprehensive pet insurance coverage is when they are young and healthy. Insuring a puppy means you are much more likely to avoid the dreaded "pre-existing condition" exclusion for genetic or hereditary conditions common to the breed. If your Bull Terrier develops a heart murmur at eight weeks or a rising UPC ratio at two years, and you don't have insurance in place before these issues are noted by a vet, any future care for those conditions will almost certainly be excluded from coverage.
Many breeders understand the importance of early health screening and provide records of initial vet checks, BAER tests for deafness, and even preliminary heart checks. These records can be invaluable when applying for insurance. It demonstrates a baseline of health. The moment you pick up your Bull Terrier puppy, or even before, is the time to start researching and enrolling in a policy. Don't wait until that first sniffle or limp, because by then, it could be too late to secure coverage for what might become a lifelong issue.
Think of it like this: if you insure your Bull Terrier puppy at 10 weeks old, and at their 6-month check-up, the vet detects a subtle heart murmur that requires an echocardiogram and lifelong medication, your insurance policy, if started early enough, would likely cover those expenses (after your deductible and according to your reimbursement rate). However, if you waited until after the 6-month check-up and the murmur was detected, then tried to get insurance, that heart condition would be deemed pre-existing. This is why insuring a young, healthy puppy is non-negotiable for Bull Terrier owners.
Congenital and Hereditary Conditions: A Closer Look
This is where Bull Terriers particularly benefit from robust pet insurance. Congenital conditions are present from birth, while hereditary conditions are passed down through genetics. Both are prevalent in the Bull Terrier breed and can be very expensive to treat. Policies vary widely on how they handle these. Some insurance providers cover congenital and hereditary conditions as long as they aren't pre-existing (i.e., symptoms appeared after enrollment and waiting periods). Others might have specific exclusions or limitations. It's crucial to read the fine print.
When researching policies, specifically ask about their stance on conditions like Hereditary Nephritis, Mitral Valve Dysplasia, and even conditions like Patellar Luxation, which Bull Terriers can also be prone to. You want a policy that clearly states it covers these types of conditions as long as they manifest after your enrollment. This is why getting insurance early, when your Bull Terrier puppy is still considered 'clean' from a medical standpoint, is so paramount.
For example, imagine you adopt a Bull Terrier puppy and get a policy from Healthy Paws. Their comprehensive accident and illness plan, for instance, typically covers hereditary and congenital conditions as long as the signs and symptoms were not present prior to enrollment or during the waiting period. This means if your pup develops a noticeable kidney issue at age two that wasn't previously detected, Healthy Paws would likely cover the diagnostics and treatment. This level of coverage is exactly what you're looking for to protect against the specific genetic lottery Bull Terriers can face.
Behavioral Issues and Their Insurance Implications
Bull Terriers are renowned for their unique personalities – they can be stubborn, clownish, and sometimes prone to behaviors that go beyond normal puppy antics. While pet insurance primarily focuses on physical health, some policies do offer coverage for behavioral issues. This could include consultations with veterinary behaviorists, prescribed medications, or even some types of training related to diagnosed behavioral conditions.
It’s worth noting that simply signing up for What Training Classes Cost a Bull Terrier Owner or addressing basic puppy mischief won’t typically be covered. However, if your Bull Terrier develops a diagnosable behavioral disorder, such as severe separation anxiety that leads to destructive chewing, or compulsive tail chasing (which, in Bull Terriers, can sometimes be a form of seizure activity rather than just play), then a policy that includes behavioral coverage could be a real asset. These specialist consultations and medications can be just as costly as treating a physical illness.
Consider a scenario where your Bull Terrier puppy starts to develop severe separation anxiety whenever you leave the house, tearing up furniture and injuring himself in his distress. If your vet diagnoses this as a clinical anxiety disorder, and recommends medication and consultation with a veterinary behaviorist, an insurance policy that includes behavioral therapy could help offset these significant costs. Without such coverage, you'd be paying out of pocket for specialist fees that often run into the hundreds per session, plus medication costs. Always check the policy details for any limitations on behavioral coverage, as it's not a standard inclusion in all plans.
Tailoring Your Policy to an Adult Bull Terrier's Needs
As your Bull Terrier moves past its boisterous puppy phase and into adulthood, their health needs and, consequently, your insurance considerations, will shift. While the ideal time to get insurance is as a puppy, it's never too late to explore options, especially if you're taking on an adult Bull Terrier or looking to update existing coverage.
Age-Related Exclusions and Higher Premiums
Unfortunately, just like with people, insuring an older pet typically comes with higher premiums. As Bull Terriers age, their risk of developing various health conditions increases, and insurance companies factor this into their pricing. You might also find that some policies have age limits for initial enrollment, or they might exclude certain conditions that are common in senior dogs if the policy is purchased later in life. This isn't meant to penalize older pets, but rather reflects the actuarial risk involved.
If you're considering insuring an adult Bull Terrier, be prepared for more questions about their veterinary history. Any conditions they've been diagnosed with or treated for in the past will likely be considered pre-existing. This doesn't mean insurance isn't worth it; it just means you need to be very clear about what will and won't be covered. For new, unforeseen accidents or illnesses, an adult Bull Terrier can still benefit immensely from a comprehensive policy, even if it carries a higher monthly cost.
Imagine you've adopted a wonderful 5-year-old Bull Terrier from a rescue. He's a sweet, calm boy, but he comes with a history of occasional ear infections, which were treated a year ago. If you get an insurance policy for him now, those ear infections would likely be considered pre-existing, and future treatments for them wouldn't be covered. However, if he suddenly develops a new condition, like a tumor or diabetes, the insurance would still be invaluable for those unexpected, new health challenges. This is a common scenario when adopting, and it's important to understand these limitations from the outset.
Managing Chronic Conditions with Existing Coverage
If your Bull Terrier was insured as a puppy and later develops a chronic condition like Hereditary Nephritis or a heart condition, having existing coverage is a game-changer. These conditions often require lifelong management, including regular vet visits, diagnostic tests, and expensive daily medications. Your insurance policy, assuming the condition wasn't pre-existing, will typically continue to cover these ongoing costs, subject to your deductible, reimbursement rate, and annual limits.
This is where the benefit of an early, comprehensive policy truly shines. Without it, managing a chronic illness in a Bull Terrier could lead to substantial financial strain over their lifespan. With insurance, you can focus on providing the best possible care for your beloved companion, knowing that a significant portion of the continuous expenses will be covered. Always keep track of your policy's annual limits and renewal dates to ensure continuous coverage for chronic conditions.
For instance, your Bull Terrier, insured since puppyhood, is diagnosed at age three with Hereditary Nephritis. This is a devastating diagnosis, and managing it can involve special renal diets (often recommended by vets, which brands like Chewy or Ollie might supply if they meet the veterinary nutritional profile), ACE inhibitors, blood pressure monitoring, and frequent lab work. If your policy has good coverage for chronic illness, a substantial portion of these lifelong costs will be reimbursed. This significantly eases the burden on your family and allows you to prioritize your dog's quality of life. Without insurance, these are the costs that contribute heavily to What Kidney Failure Costs a Bull Terrier Owner.
Wellness Plans: Are They Worth It for Bull Terriers?
Separate from accident and illness insurance, some providers offer "wellness plans" or "routine care add-ons." These are designed to cover the predictable costs of pet ownership, such as annual exams, vaccinations, routine bloodwork, flea and heartworm prevention, and sometimes even dental cleanings. Unlike insurance, which is for unexpected events, wellness plans are budgeting tools for planned expenses.
For Bull Terriers, who benefit from regular check-ups, yearly kidney screens, and diligent flea/tick prevention due to their sensitive skin, a wellness plan can be beneficial. However, it's crucial to do the math. Compare the annual cost of the wellness plan to the actual cost of the services it covers at your vet's office. Sometimes, you might pay more in premiums than you receive in benefits. For Bull Terriers, particularly, consider if the plan covers things like the annual UPC screen or a specific kind of dermatology consultation that might be routine for their breed.
Before adding a wellness plan, list out your Bull Terrier's expected routine costs for the year: annual exam, vaccinations, parasite prevention, and maybe a routine urinalysis. Then, compare that total to the wellness plan's annual price. For some owners, the convenience of monthly payments and knowing these costs are covered is worth the potential slight premium. For others, simply setting aside money in a savings account might be more cost-effective. It's a personal choice, but don't assume a wellness plan is always a money-saver without doing the calculations for your specific situation.
Comparing Insurance Providers for Bull Terrier Owners
Choosing the right pet insurance provider for your Bull Terrier isn't a decision to rush. Each company has its own nuances, and what works well for one breed or owner might not be the best fit for another. You're looking for a provider that understands the unique needs of a Bull Terrier and offers robust, reliable coverage.
Researching Breed-Specific Coverage Details
This is perhaps the most critical step for Bull Terrier owners. Given their predispositions to conditions like Hereditary Nephritis, heart disease, and skin allergies, you need to ensure the policy explicitly covers these types of hereditary and congenital conditions. Don't just assume; ask directly or scrutinize the sample policy documents. Look for language that clearly states how these conditions are handled, especially if they are not considered pre-existing at the time of enrollment.
Some companies might have exclusions for certain conditions or specific breeds, or they might cap lifetime payouts for particular hereditary issues. You want a provider that offers comprehensive, lifelong coverage for chronic and hereditary conditions that manifest after enrollment. Read reviews from other Bull Terrier owners if possible, as their experiences with claims related to breed-specific issues can be very telling.
For example, when looking at providers like Healthy Paws, you'd want to confirm that their comprehensive plans cover hereditary conditions as long as they aren't pre-existing. You might compare this to another provider that has strict limitations on conditions like heart disease after a certain age. Understanding these subtle differences can make all the difference when your Bull Terrier is diagnosed with something like Hereditary Nephritis Takes Bull Terriers in Their Prime, as the ongoing costs will be significant.
Customer Service and Claims Process
Beyond the policy details, consider the practical aspects of dealing with an insurance company. How easy is it to submit a claim? Do they offer direct deposit for reimbursements? What is their typical turnaround time for processing claims? When your Bull Terrier is sick or injured, the last thing you want is a convoluted, slow, or frustrating claims process. Good customer service can significantly reduce stress during an already difficult time.
Look for providers with a reputation for excellent customer service and a straightforward claims process. Many companies now offer online portals or mobile apps for submitting claims, which can be very convenient. Some even offer direct vet payment, meaning you only pay your portion (deductible and co-pay) at the time of service, and the insurance company handles the rest directly with the vet. This can be a huge financial relief during expensive emergencies or treatments.
Imagine your Bull Terrier suddenly falls ill and needs emergency surgery. The vet bill is substantial. Having a smooth claims process, like with a company known for fast reimbursements, means you're not waiting weeks for your money back while also trying to manage a sick pet. Check reviews and testimonials specifically regarding claims handling to gauge a company's reliability and responsiveness.
Exploring Multi-Pet Discounts and Customization
If you're a multi-Bull Terrier household (and many Bull Terrier owners find it hard to stop at just one!), look for providers that offer multi-pet discounts. This can add up to significant savings on premiums over time. Also, consider the level of customization available for policies. Can you adjust deductibles, reimbursement percentages, and annual limits to fit your budget and risk tolerance?
Being able to customize your policy allows you to strike a balance between premium cost and coverage level. A higher deductible will typically mean a lower monthly premium, but you'll pay more out-of-pocket before coverage kicks in. Similarly, a lower reimbursement percentage will reduce your premium but increase your co-pay. Weigh these factors carefully against your financial situation and your Bull Terrier's anticipated health needs.
For instance, if you have two Bull Terriers, a provider like Healthy Paws might offer a discount for insuring both dogs under their plans. You could then customize each dog's policy: perhaps a higher deductible for your young, healthy pup to keep premiums low, and a lower deductible for your senior Bull Terrier, for whom vet visits might be more frequent as you are Caring for a Bull Terrier Past Eight. This flexibility ensures you're getting the best value and coverage tailored to each individual Bull Terrier in your family.
Beyond Insurance: Financial Planning for Bull Terrier Health
While pet insurance is a powerful tool for managing unexpected veterinary costs, it's important to remember it's just one piece of the financial puzzle. A comprehensive approach to budgeting for your Bull Terrier's health involves more than just a monthly premium. It's about proactive planning, understanding long-term costs, and ensuring you have a safety net for everything insurance might not cover.
Building an Emergency Fund
Even with the best pet insurance, there will always be out-ofpocket expenses. You'll have your deductible, your co-pay (the portion not reimbursed), and potentially costs for services not covered by your policy (like certain wellness procedures, specialized diets not prescribed for an illness, or grooming). This is where a dedicated emergency fund for your Bull Terrier becomes invaluable.
Think of it as your Bull Terrier's personal rainy-day fund. This money can cover those gaps in insurance coverage, the annual deductible before a big claim, or even unexpected emergency care if you haven't yet met your deductible for the year. Having a few thousand dollars set aside specifically for your dog's health can alleviate immense stress during a crisis, allowing you to focus on your Bull Terrier's well-being rather than scrambling for funds.
For example, your Bull Terrier might swallow something it shouldn't, requiring an emergency vet visit and endoscopy, costing a couple of thousand dollars. If you haven't yet met your annual deductible, or if the procedure isn't fully covered, your emergency fund can bridge that gap immediately. This avoids having to put large vet bills on a credit card or delay necessary treatment, which nobody wants to do for their beloved companion. It also provides a buffer for smaller, routine expenses not covered by insurance. This proactive saving is key to truly understanding What a Bull Terrier Costs Over Its Lifetime.
Understanding the True Cost of Long-Term Care
Bull Terriers, with proper care and a bit of luck, can live for The Ten to Fourteen Years a Bull Terrier Gets. Over such a long lifespan, health needs will inevitably change. Understanding the potential long-term costs, especially for chronic conditions, allows for more realistic financial planning. Even with insurance, chronic conditions can incur significant out-of-pocket expenses due to deductibles and co-pays over many years.
Consider conditions like chronic allergies, arthritis in older age, or even diabetes, which may require daily medication, special diets, and regular monitoring. While insurance helps significantly, the cumulative cost of your 10% or 20% co-pay over ten years can still be substantial. Budgeting for these ongoing costs, even small ones, ensures you can continue to provide consistent, high-quality care without financial strain.
Imagine your Bull Terrier develops chronic skin allergies early in life. Even with excellent insurance, you're likely paying your deductible each year, plus a 10-20% co-pay on monthly allergy medications, special shampoos, and vet check-ups. Over a decade, these small co-pays add up considerably. Being aware of this long-term financial commitment allows you to adjust your budget or savings accordingly, ensuring your Bull Terrier receives continuous care without interruption. For veterinary prescribed foods, don't forget to check retailers like Chewy or Ollie that might offer various specialized diets or discounts on regular food purchases that contribute to overall health.
Proactive Health Management to Reduce Risks
An ounce of prevention is worth a pound of cure, and this adage holds especially true for Bull Terriers. While you can't prevent genetic predispositions, proactive health management can significantly reduce the severity or frequency of other health issues, potentially lowering your vet bills and insurance claims over time.
This includes providing a high-quality, balanced diet (perhaps from a brand like Ollie if a fresh food diet is suitable and vet-approved, or exploring options on Chewy for specialized kibble), ensuring adequate but not excessive exercise to prevent joint issues, maintaining a healthy weight, and staying on top of all recommended preventative care like vaccinations, parasite control, and regular dental cleanings. Routine vet check-ups allow for early detection of problems, which can often be treated more effectively and at a lower cost than advanced diseases. Regular checking of A Bull Terrier's Skin Is Its Weakest Point can catch issues before they escalate.
For instance, keeping your Bull Terrier at a healthy weight prevents unnecessary strain on their joints, which can reduce the likelihood of conditions like arthritis or patellar luxation as they age. Similarly, diligently using flea and tick prevention can prevent parasitic skin reactions that might otherwise lead to expensive dermatology visits. Proactive care is not just about saving money; it's about giving your Bull Terrier the best possible chance at a long, healthy, and happy life, minimizing the need for those costly insurance claims in the first place. Knowing What Most Bull Terriers Die Of can also help guide your preventative strategies.
Disclaimer
This article is for general informational purposes only and does not constitute professional advice. Laws, prices and regulations vary by location and change over time. Consult a qualified professional for guidance on your specific situation.